


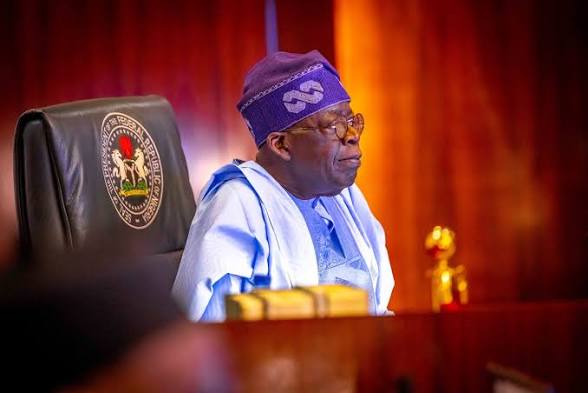
President Bola Tinubu has approved a new regulatory and fiscal framework designed to attract up to $50 billion in investment into Nigeria’s deep offshore oil and gas sector.
The framework, known as the Deep Offshore Oil and Gas Projects Incentives, is meant to give investors greater certainty and revive major offshore projects stalled by regulatory uncertainty, high development costs and competition from other oil-producing nations.
Presidential spokesman Bayo Onanuga said the framework replaces the old system of project-by-project negotiations with a rules-based structure backed by a new tax remission order.
The government said the initiative would improve Nigeria’s competitiveness for international capital and create a more predictable environment for offshore oil and gas developments.
Shell’s long-delayed $10 billion Bonga South West project is among the first expected to benefit, with a final investment decision projected for 2027.
The approval also empowers NNPC Ltd to amend eligible production-sharing contracts with participating producers under the new framework.
Qualifying projects will be required to prioritise local execution where feasible, a move the government says will create jobs and strengthen domestic supply chains in the oil and gas industry.
The Tinubu administration has been working to restore investment in Nigeria’s upstream petroleum sector following years of declining capital inflows and delayed major projects. The new policy is expected to support fresh offshore developments, boost oil production and strengthen government revenues while positioning Nigeria for long-term energy sector investment.
READ ALSO:
- Trump, Xi, Putin Hold First Trilateral Summit, Discuss Nuclear Arms Cuts
- “Holy Ground, Unholy Hardship and Tinubu’s 2027 Headache.” | By Blaise Udunze
- Irresponsible Communication Endangers Democracy, Lives, Says Okonkwo
- 2,560 Kano Inmates Regain Freedom Through Legal Aid Council Intervention
- INEC Deploys 186,277 BVAS Machines To States Ahead Of 2027 Polls
